
A $2 million common contractor pays subcontractors, invoices purchasers, points worker playing cards, and retains its personal books. Most banks nonetheless serve this enterprise the best way they serve a shopper, simply with a bigger steadiness. Owners fill the gaps by stitching collectively a dozen or extra apps.
Digital banks competing for this market are pulling extra of those jobs into the banking expertise, constructing some instruments themselves and embedding companions for the remainder. Bluevine, which started in small enterprise lending, has spent the final six years constructing a broader suite of banking merchandise round its checking account.
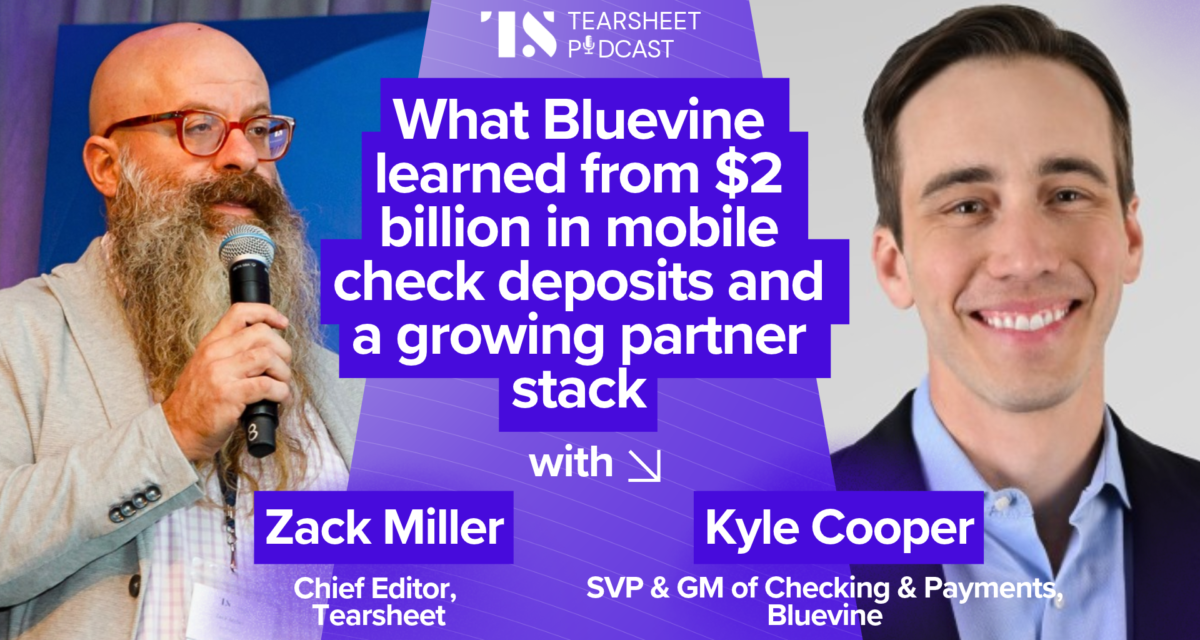
On the Tearsheet podcast, Kyle Cooper, Bluevine’s SVP and GM of Checking and Payments, mentioned small enterprise homeowners’ underlying wants have stayed constant even because the merchandise round them have modified. “Business owners always care about saving themselves a headache, getting more financial value,” he mentioned. But the bar for delivering each retains transferring. “We are seeing that expectations are constantly rising from small businesses in terms of the quality of the offering they have in front of them.”
Cooper walked by means of how Bluevine decides what to construct, what to embed, and what to depart to others, in addition to what the corporate has learned about operating a financial institution with out branches.
Watch the total podcast
Listen to the total podcast
Subscribe: Apple Podcasts I SoundCloud I Spotify
Businesses with complexity want greater than a consumer-style account
Bluevine welcomes brand-new companies, Cooper mentioned, and has constructed its account-opening course of to be quick and easy for them. Those early wants typically resemble shopper wants, which is how giant banks have lengthy handled small companies of each dimension.
The firm’s focus extends properly past that place to begin. “When you think about a $2 million a year general contractor or a million dollar a year dry cleaning business or a medical practice, these are businesses that have a lot of complexity to them,” Cooper mentioned. Those operators pay many workers and distributors, obtain funds from completely different sources, and run different programs alongside their financial institution accounts.
Bluevine goals to maintain prospects on the platform as their companies develop extra complicated. A more moderen enterprise may begin with a checking account that pays yield on balances, then add accounts payable instruments that carry in an accountant or bookkeeper, invoicing, or worker playing cards with spending limits. “As needs become more complex, the intent is that they don’t need to move somewhere else,” Cooper mentioned. He described Bluevine as able to assist companies with a crew and annual income reaching properly into the seven- and even eight-figure vary.
Customer demand shapes the construct, embed, or refer determination
Cooper described three paths Bluevine approaches a buyer want. Sometimes it builds a product itself. In different circumstances, a few established gamers already do the job properly, and enterprise homeowners already use them, making partnerships the higher choice. Some wants fall someplace in between.
“We wouldn’t do anything if there weren’t customer demand for it,” Cooper mentioned. One early instance was a two-way QuickBooks sync, which Bluevine constructed as a result of many enterprise homeowners already relied on the software program. More not too long ago, prospects requested for assist getting paid, so Bluevine constructed its personal invoicing software program, with funds processing powered by Stripe. It additionally introduced an accounting product powered by Xero, embedded in the Bluevine expertise and priced considerably beneath standalone software program.
Not each buyer request ensures a new product. Bluevine weighs whether or not it’s positioned to offer a good service and how shut the request sits to what it already affords. Business insurance coverage is one instance: Bluevine is neither a provider nor a dealer, so it companions with corporations in that area. The identical goes for HR programs. In these circumstances, Cooper mentioned, the corporate is “playing matchmaker and helping our customers find something that will work well for them.” That strategy can change over time as demand grows and the corporate’s readiness to serve these wants in-house evolves.
Embedding eases setup and day-to-day use
Cooper separated the advantages of embedding into two levels: signing up for a service and utilizing it on an ongoing foundation. For setup, controlling the consumer expertise means fewer clicks and no must ask prospects for info Bluevine already holds, which a handoff to an outdoor service would require. He pointed to worldwide funds, the place a partner powers the potential however it appears like a part of Bluevine, and mentioned the corporate sees higher setup completion as a outcome.
Ongoing use is the second achieve. Cooper is optimistic that Bluevine Accounting, which sits contained in the buyer’s banking ledger, will match extra naturally into an proprietor’s routine than separate software program that requires switching again and forth. The outcome, he mentioned, is “less overhead, less switching cost” in the day by day administration of funds. The product was in beta on the time of the dialog, with common availability anticipated inside weeks, so Cooper didn’t have utilization information to share.
Payments acceptance offers Bluevine the chance to sit down nearer to the middle of a enterprise’s monetary operations, the place a enterprise holds cash, pays individuals, and accepts funds. Bluevine’s invoicing software program is free to prospects as quickly as they open a checking account. Customers who need to settle for funds full an extra setup with Stripe and handle the whole lot inside Bluevine. Launched between one and two years in the past, the product now has “many thousands of customers using that product, tens of millions in monthly GMV,” Cooper mentioned.
Bluevine is cautious to make sure that a partner’s product doesn’t damage the expertise it has constructed for patrons. The embedding course of is subsequently meticulous. “It needs to not degrade the excellent digital experience that we have built for our customers,” Cooper mentioned. This means being attentive to look, really feel, and responsiveness, and a strict strategy to friction. The firm weighs how a lot fit-and-finish work and deeper technical integration a given product deserves and validates buyer curiosity earlier than making bigger investments. Once Bluevine decides to embed a product, Cooper mentioned, it “needs to look and feel like Bluevine.”
Partnerships require alignment as properly. Cooper mentioned either side should agree on the end-to-end buyer expertise, how assist points might be resolved, “who’s on the hook for what,” and how the 2 groups will talk. These conversations between companions proceed after launch. “It’s an ongoing investment with partners,” he mentioned, including that the overall availability launch of Bluevine Accounting is “the start of the journey in many ways.”
A digital financial institution’s polished expertise takes years of funding
Cooper mentioned most small companies in the U.S. nonetheless financial institution with a giant nationwide financial institution, a regional financial institution, or a credit score union, and lots of them get “a pretty clunky experience that is years behind what we’re offering.” Building a higher digital different takes sustained spending. “We’ve invested a lot of money to make it look easy,” he mentioned.
Mobile check deposit reveals the dimensions of Bluevine’s effort. Over the final yr, Bluevine processed greater than $2 billion in check deposits with out branches and made 97% of them out there the identical day, with excessive deposit limits. Bluevine does this with out taking bodily custody of a check and bears the fraud losses when it will get a determination improper. This form of efficiency comes solely after “you’ve invested significantly over a period of years,” in line with Cooper.
However, gaps stay. Cash-heavy companies are one of many few buyer segments the place an proprietor should still need a relationship with a financial institution or credit score union that has branches, even when meaning sustaining two relationships. Closing these gaps is a part of how Bluevine thinks about extending its product to serve nearer to 100% of small companies slightly than 90%.
Most homeowners worth belief and comfort over assembling the most effective of every instrument
One threat of proudly owning extra of a buyer’s workflow is that prospects change into tougher to maneuver elsewhere. Cooper addressed the tradeoff by describing the homeowners Bluevine serves. Some are true optimizers who assemble the most suitable choice for each operate and could find yourself with 12 to 18 apps. In Cooper’s expertise, that group is small.
“The vast majority of them don’t want to think about their banking and their financial services,” he mentioned. They need monetary worth and ease of use with out the complications, which covers each day by day friction and the second when one thing breaks. Many homeowners are open to reaching that outcome by means of one or two suppliers they belief. Cooper famous that the tendency to open a enterprise account on the identical financial institution that holds the proprietor’s private account comes from the identical impulse.
That shapes Bluevine’s strategy. “We need to deliver a better product than the incumbents,” Cooper mentioned. “If we earn trust, then we will have the right to do more and more for our customers over time.”
What comes subsequent
Cooper mentioned Bluevine has one other vital partnership, not but introduced, that it expects to go reside across the finish of the yr. He described it as in conserving with the remainder of the dialog: doing extra for patrons in a means that feels simple and builds belief.
The firm additionally continues to speculate in what it calls “the guts of banking,” together with cash motion, the digital expertise, and fraud instruments. “That work never stops,” he mentioned. Even a wonderful financial institution has annoying moments for patrons, so lowering them is steady work, aimed toward making banking “feel more seamless and more rewarding for customers.”