In automobile importing, business homeowners should discover the automobile and pay the public sale home, which could possibly be overseas. This proved tougher than anticipated for Sheriff Adedokun, a serial entrepreneur who based Clea, a cross-border payments platform for African companies.
Africa’s fragmented cross-border payments panorama was not new. Businesses buying and selling internationally had relied on banks or different monetary intermediaries to maneuver cash between markets. By 2022, when Adedokun began importing automobiles from the United States, Nigerian fintechs have been constructing merchandise to make worldwide payments simpler. However, the accessible choices didn’t all the time work for the transactions he wanted.
“I tried to use some of the fintech platforms in Nigeria, but it didn’t work because most of my payments were rejected,” Adedokun informed TechCabal in an interview. “Then I had to go to the bank, fill a form, and try to do the transfer. There was also a limit on sending international transfers from Nigerian banks.”
He defined that US automobile public sale platforms required payments to come back immediately from the particular person or business shopping for the automobile, as third-party transfers could possibly be rejected.
Car importation was one instance of a deluge of companies that needed to pay suppliers earlier than their orders could possibly be shipped. Total imports stood at over ₦15 billion ($11.1 million) within the first quarter of 2025, based on National Bureau of Statistics (NBS) information.
In 2024, Adedokun based Autoclear, a business that helped prospects supply automobiles and pay US public sale platforms. While working with importers, he observed additionally they needed to pay transport firms, freight forwarders, and brokers, every with its personal fee necessities and separate from the public sale homes the place they purchase the vehicles.
So, he teamed up along with his longtime good friend Sidney Egwuatu to construct Clea, a cross-border payments platform to serve African companies importing items from abroad. The firm developed the product in stealth earlier than publicly launching in December 2025.
How Clea strikes cash throughout borders
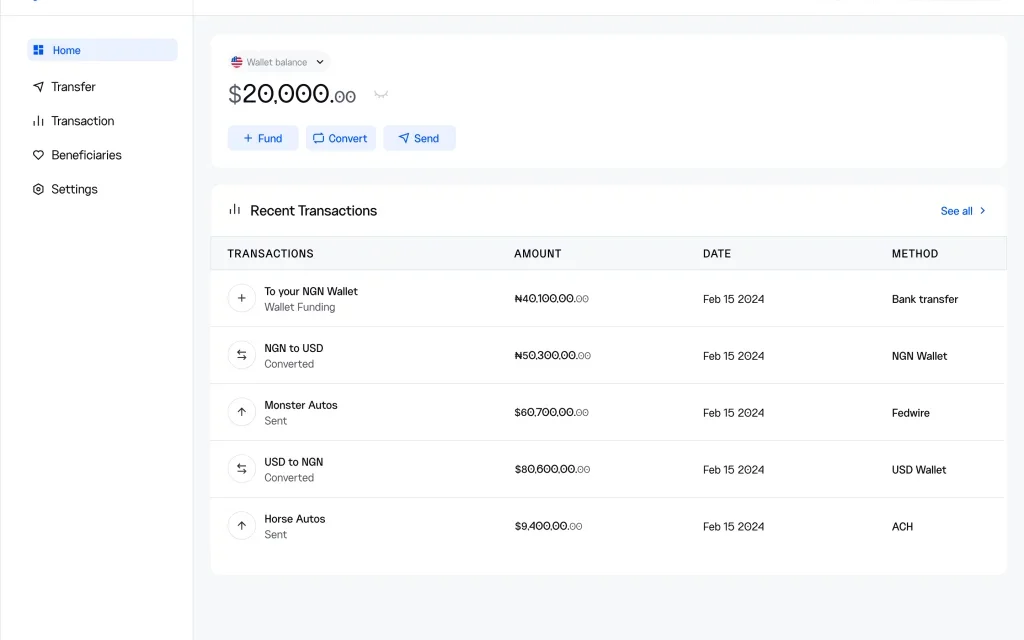
Clea permits companies to handle worldwide provider payments from a single platform. After signing up and finishing verification, a business can fund its account in naira from a Nigerian checking account, convert the funds into the required forex, and add its abroad provider as a beneficiary. During a dwell product demonstration, Adedokun confirmed that the platform helps currencies together with the US greenback, British pound, euro, and Chinese yuan.
To add a new provider, a buyer supplies particulars such because the recipient’s deal with, nation, and the character of their relationship with the beneficiary. After including the beneficiary, the client can provoke a fee utilizing the accessible fee routes for that vacation spot. Adedokun mentioned payments to US beneficiaries may undergo ACH, Fedwire or the Real-Time Payments (RTP) community, whereas payments to different locations could possibly be routed via SWIFT.
Stablecoins kind a part of the infrastructure Clea makes use of to maneuver worth between the completely different elements of this fee course of. Adedokun mentioned the platform is designed to maintain this complexity out of sight, permitting prospects to give attention to funding their accounts in naira and making certain suppliers obtain the agreed overseas forex. Customers also can fund their greenback wallets immediately with stablecoins, together with USDT and USDC, via supported blockchain networks.

Africa’s cross-border payments ecosystem has seen rising stablecoin use for remittances and business settlements. Flutterwave, a Nigerian payments infrastructure firm, has begun exploring an integration of USDC settlement into its payments infrastructure. In February, Onafriq partnered with Conduit to make use of USDC for cross-border payments and payouts to worldwide companions.
“Stablecoins are additionally a part of our settlement infrastructure,” Adedokun defined. “They allow value to move efficiently between parts of the payment stack, but our customers don’t need to understand stablecoins or interact with crypto. They simply know that they were funded in naira and their supplier received dollars, pounds, euros or yuan.”
In August, Clea launched a Vendor Payments characteristic for companies that repeatedly pay the identical abroad firms. Adedokun mentioned the product emerged from a deeper understanding of buyer wants, formed by observing how companies used the platform. Clea serves wholesalers, producers, electronics distributors, trend companies, equipment importers and African companies that depend upon worldwide suppliers.
“Initially, we thought speed and FX access were the biggest problems,” he mentioned. “ They are still very important, but once customers started using Clea repeatedly, we realised that trust, payment identity, reconciliation and supplier management are equally important.”
With Vendor Payments, prospects can choose the provider from a record of preconfigured distributors whose fee data the platform maintains. They nonetheless want to offer the transaction-specific reference the provider requires, reminiscent of a purchaser quantity or lot quantity, earlier than authorising the fee.
According to Adedokun, Vendor Payments helps US-dollar payments to chose suppliers within the United States, together with automobile public sale platforms Copart and IAA.
“If thousands of importers are paying the same shippers, auction companies and suppliers, it doesn’t make sense for every importer to establish that relationship independently every time,” he mentioned. “Once the vendor already exists on Clea, we can simplify the transaction for both sides: fewer incorrect account details, faster reconciliation, better visibility and potentially much faster settlement.”
Clea is betting on importers
Clea makes cash primarily from transaction charges and the margin between the change charge it sources overseas forex at and the speed it gives prospects. Adedokun mentioned the corporate is constructing a transaction-driven business, the place greater fee volumes and extra environment friendly infrastructure may help decrease its underlying prices and enhance pricing over time. Since its launch, Clea says it has processed greater than $50 million in payments.
“We have to be very disciplined about pricing because our customers understand FX extremely well. These are businesses moving significant amounts of money, so even a small difference in the exchange rate matters,” Adedokun mentioned.
Clea is competing with fintechs reminiscent of Verto, Raenest and Grey, which provide companies multi-currency accounts and worldwide payments. In February, Olayemi Cardoso, Nigeria’s Central Bank (CBN) governor, stated that the nation’s common month-to-month diaspora remittance inflows are about $600 million, displaying the size of cross-border cash motion in Nigeria. Adedokun argued that Clea’s focus is narrower: it’s constructing across the particular wants of importers, relatively than providing a general-purpose worldwide payments product.
“We don’t think of Clea as another generic international money-transfer product. We are building specifically around the workflow of an importer,” he mentioned. “Our objective is to stay competitive on FX and fees while giving customers speed, reliability, transparency and proper payment documentation.”
When requested about regional enlargement, Adedokun mentioned the corporate is prioritising development in Nigeria. Its instant plans embody increasing the seller community, strengthening its fee infrastructure, bettering transaction effectivity and lowering the underlying price of payments.
“There’s a temptation with an African fintech company to announce ten countries very quickly, but there is still a huge amount of market for us to capture in Nigeria,” Adedokun mentioned. “Our immediate priority is to deepen our presence in Nigeria, where we still see considerable opportunities to serve businesses involved in international trade. Ultimately, we want Clea to become the preferred financial infrastructure partner for African businesses trading globally.”