
Even a tiny rise in financial institution deposit charges might gradual stablecoin development considerably. According to a current examine by the Bank for International Settlements (BIS), a one foundation level improve in financial institution rates of interest reduces the expansion in market capitalization of stablecoins by about 3% over ten weeks.
Given that the general development is at roughly 15% yearly, this lower would cut back the quantity of development to be roughly 12% yearly. USD Coin [USDC] reveals better sensitivity, with development declining 4.8 proportion factors, in contrast with USDT’s 1.9-point discount.
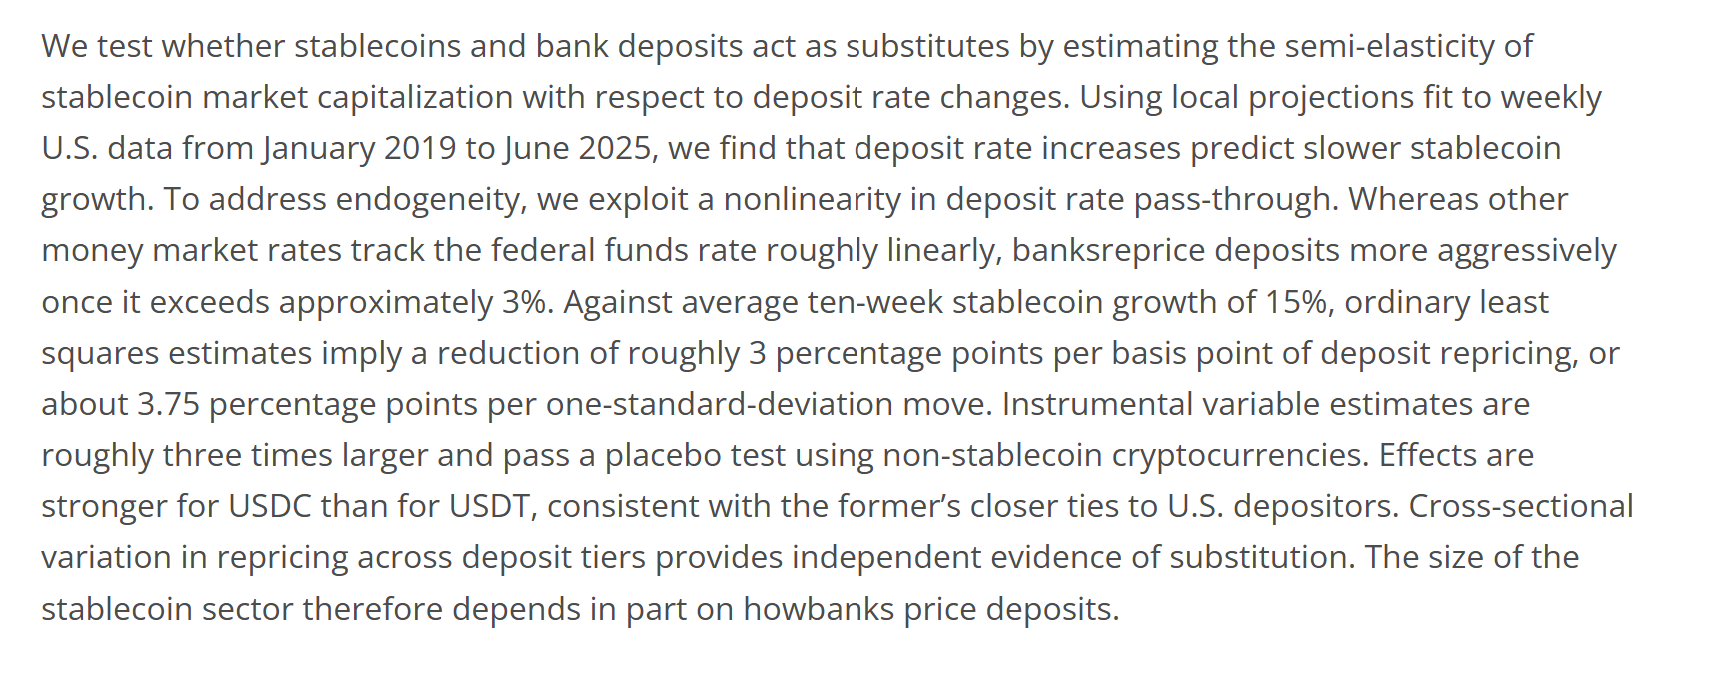
This distinction highlights USDC’s nearer ties to U.S. customers and establishments. Moreover, larger financial institution yields make deposits extra enticing relative to stablecoins. Yet, the impact stays particular to stablecoins, as researchers discovered no vital hyperlink with different cryptocurrencies.
Therefore, rising rates of interest might decelerate the expansion of recent steady cash however is not going to eradicate the present provide of stablecoins.
Visa expands USDC cost rails
On the opposite hand, whereas financial institution charges problem stablecoin demand, Visa’s stablecoin expansion highlights rising real-world cost utility.
For instance, Visa Direct at present permits cost of wages or purchases made utilizing USDC-funded cross-border payouts in additional than 180 nations. Inyo Global is their first associate.
This characteristic might present a technique for acquiring extra demand for stablecoins past merely buying and selling or utilizing decentralized finance.
It also needs to enable companies to attract upon out there funds at any time, avoiding reliance on banking hours or correspondent networks.
At current, there are nonetheless over $300 billion in excellent stablecoin capitalization. If Visa continues to increase its service to incorporate extra nations and/or extra banks, it seems potential that extra demand for stablecoins might develop.
However, if the speed of adoption is slower than anticipated, stablecoin holders who don’t earn curiosity on their stablecoins may have to contemplate different types of stablecoins. Some of those different types of stablecoins are already paying curiosity on idle cash.
USDC cost exercise accelerates
Visa’s dollar-based stablecoin settlement quantity is already at an annualized run charge of $20 billion. That represents greater than a 15-fold increase in contrast with final 12 months.
That information means that stablecoins are shifting from purely speculative holdings to getting used for precise payments.
Still, in response to DeFiLlama information, USDC whole circulating provide stands at $72.6 billion. That stated, measuring how a lot USDC is concerned in transactional exercise is vital to figuring out whether or not stablecoins are literally supporting commerce or just accumulating wealth.
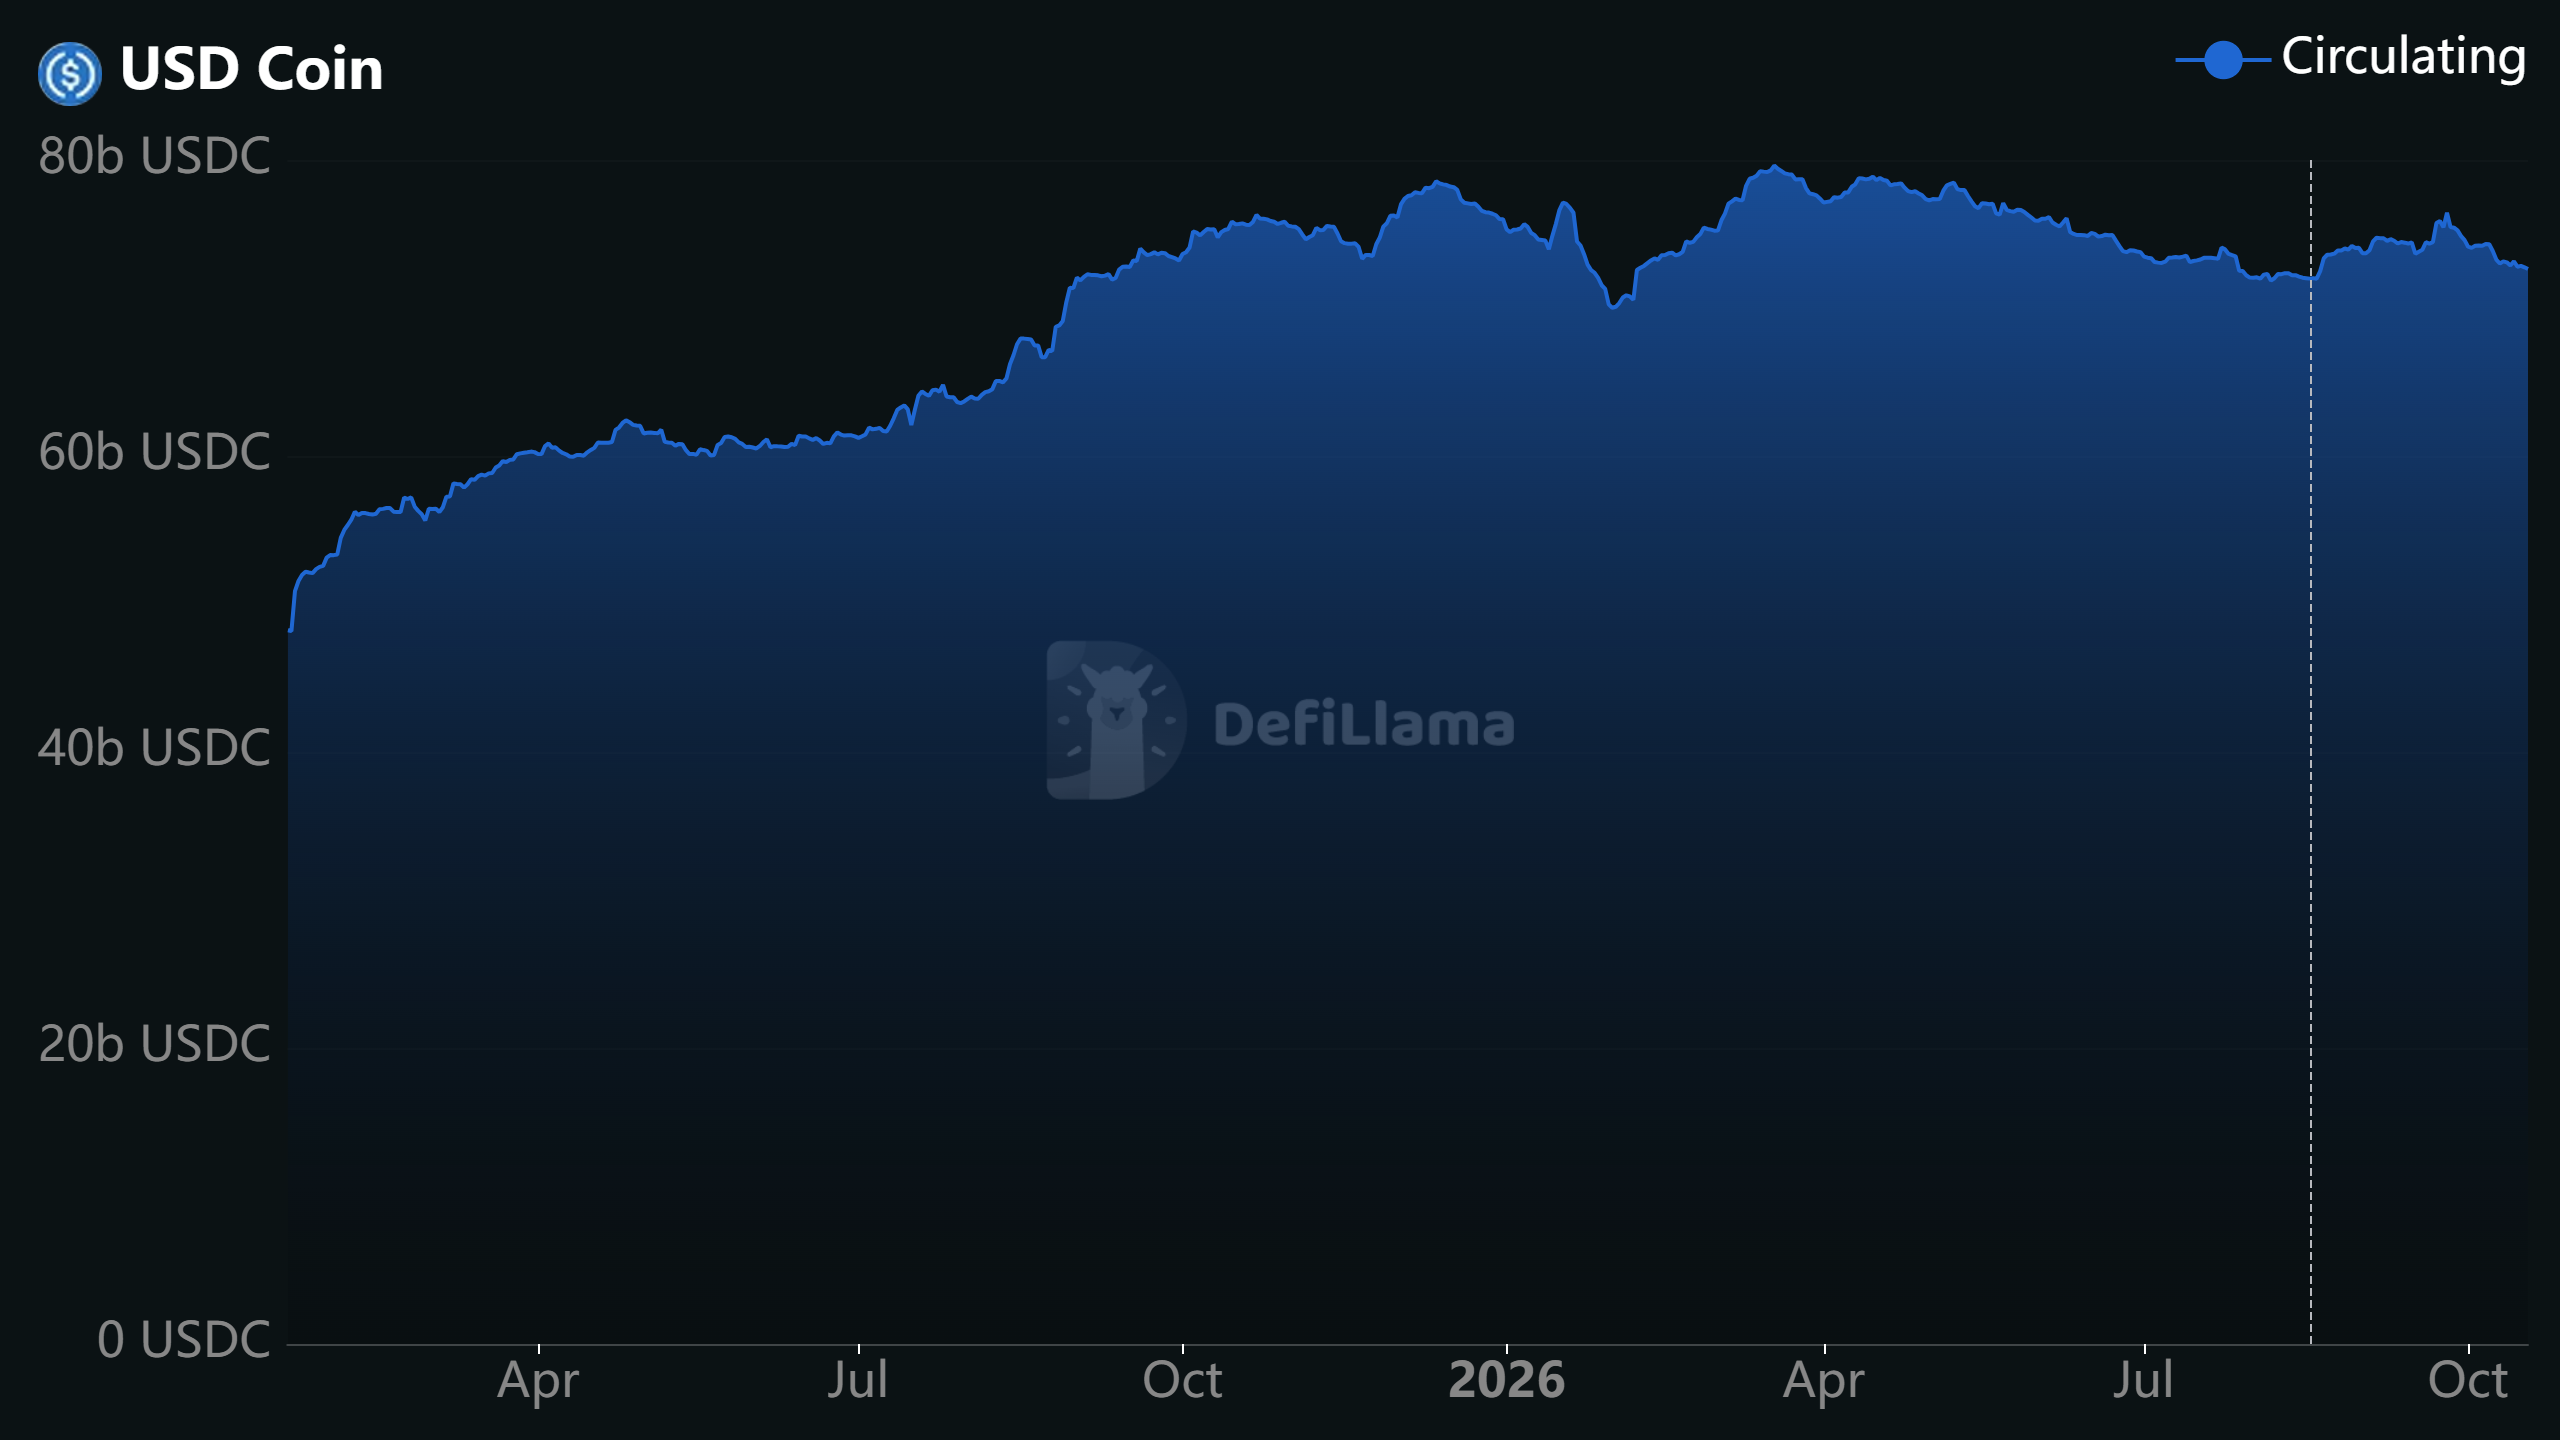
If the quantity of USDC utilized in settlements grows sooner than the circulating provide of USDC, it might start to counteract among the loss in demand because of rising deposit charges at banks.
For this pattern to proceed, retailers and others might want to proceed processing a number of transactions utilizing prefunded USDC balances.
Final Summary
-
Stablecoin development faces pressure as rising financial institution deposit charges make conventional financial savings extra enticing, slowing market capitalization growth.
-
USD Coin [USDC] cost adoption might help stablecoin demand as Visa’s settlement quantity exceeds a $20 billion annualized run charge.