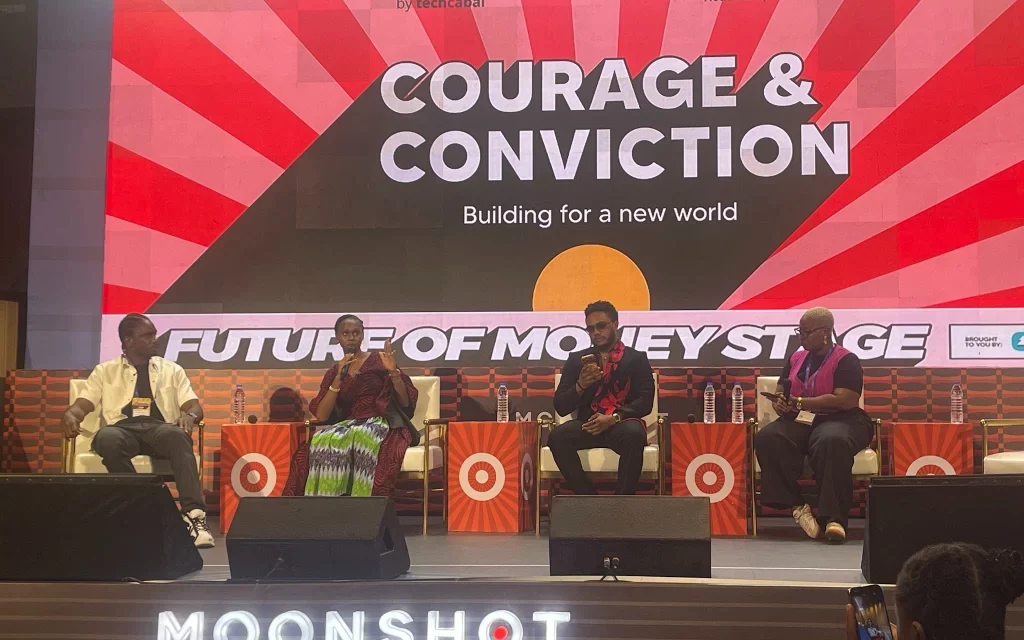
Stablecoins are giving African companies another method to pay abroad suppliers, but prices, safety issues and fragmented blockchain networks stay obstacles to wider use, trade executives instructed Moonshot by TechCabal in Lagos.
Speaking on a panel titled, “Where Are Stablecoins Creating Real Value in Africa?”, representatives from Solana Superteam Nigeria, Obiex and Hyperbridge mentioned demand was being pushed by sensible difficulties in accessing overseas foreign money and finishing worldwide funds.
Chinonso Obiefule, lead at Solana Superteam Nigeria, mentioned some Nigerian companies have been already utilizing stablecoins to pay suppliers in China when {dollars} have been tough to get hold of via typical channels.
“People want to access dollars, but they cannot do that because, obviously, dollars aren’t easily accessible, so the next best option is actually stablecoin,” he mentioned.
The attraction extends past entry to overseas foreign money. Businesses buying and selling throughout time zones additionally want to transfer funds outdoors banking hours, mentioned Odinaka Esiagu, head of buyer success and operations at Obiex.
An organization shopping for items from a Chinese provider may want to full a cost whereas its financial institution was closed, she mentioned. Stablecoins might permit it to switch funds with out ready till the following banking day.
Esiagu mentioned the know-how would enhance the pliability of sure transactions quite than get rid of the necessity for banks.
The dialogue mirrored the rising position of dollar-linked digital property in Nigeria’s monetary system. The nation obtained about $59 billion in crypto-asset inflows between July 2023 and June 2024, in accordance to the IMF.
That determine covers crypto property broadly, quite than stablecoins alone. The fund additionally estimates that Nigeria has accounted for roughly 60 per cent of stablecoin inflows into sub-Saharan Africa since 2019.
Costs and confidence
For companies, nonetheless, a brand new cost channel should provide greater than availability. Obiefule mentioned builders wanted to make worldwide transfers cheaper, safer and simpler to use.
“It should be cheaper to send money to somebody abroad or to get money from somebody abroad,” he mentioned.
Low blockchain transaction charges have been an vital consideration for firms selecting which networks to use, he added. Lower prices might make stablecoin funds commercially viable for extra companies.
Trust remained one other constraint. Esiagu mentioned experiences of cryptocurrency platforms being hacked continued to deter potential clients.
“Some people are still scared,” she mentioned.
Obiex was creating a service to assist companies construct stablecoin-based merchandise by offering technical and compliance-related assist, she added. The purpose was to permit firms to concentrate on their clients with out having to develop all of the underlying capabilities themselves.
Connecting separate networks
Seun Lanlege, chief govt of Hyperbridge, mentioned fragmentation throughout blockchains created an additional problem: funds obtainable on one community weren’t essentially readily accessible on one other.
That restricted customers’ capacity to draw on liquidity throughout platforms, complicating the promise of seamless transfers.
Lanlege mentioned Hyperbridge supplied infrastructure for shifting tokens between networks, whereas its HyperFX product used these connections to facilitate transactions throughout blockchain ecosystems.
Such methods wanted to prioritise safety and decentralisation, he argued, warning that reliance on centralised intermediaries might create vulnerabilities.
Regulation additionally stays central to the market’s growth. The IMF has known as for clearer therapy of stablecoin issuers in Nigeria, alongside stronger oversight and higher knowledge on how digital property work together with the home monetary system.
It has warned that widespread use of dollar-denominated stablecoins might weaken financial coverage transmission and create monetary integrity dangers.