

In a current growth, the Blockchain Association (BA) has urged the U.S. Congress to introduce clearer and fairer tax rules for cryptocurrencies. They consider that current rules create uncertainty and pointless compliance burdens for the 67 million Americans who maintain and use digital property.
Therefore, in a letter dated the twenty second of October, 2026, addressed to Senate and House leaders, the business group outlined its Digital Asset Tax Principles. In truth, they even known as for bipartisan laws that displays how digital property operate at present.
Besides this, the BA additionally launched TaxClarityforAmerica.com to encourage Americans to contact their elected representatives and help the proposed reforms.
What is the motive behind this?
With this transfer, the affiliation is looking for a significant ‘de minimis’ exemption to simplify taxes on small crypto transactions and cash-like tax remedy for stablecoins. This in flip is meant to scale back reporting necessities doubtlessly.
At the identical time, the BA also proposed taxing mining and staking rewards when they’re bought or disposed of, moderately than when customers initially obtain them. This is a step that will stop tax liabilities on rewards that haven’t been transformed into money.
Additionally, it needs dealer reporting necessities to apply solely to intermediaries which have custody or management of buyer property. This excludes non-custodial builders and infrastructure suppliers to defend privateness.
Key suggestion by the Blockchain Association
Another key proposal is to stop taxes from being triggered when customers switch digital property between their very own wallets, work together with good contracts, or transfer property throughout blockchains. However, this comes with a situation that their underlying financial possession stays unchanged.
The affiliation additionally helps extending wash-sale rules to crypto to stop traders from claiming synthetic losses whereas guaranteeing that on a regular basis transactions will not be unfairly penalized.
That stated, different suggestions embody permitting crypto investments in retirement accounts, clarifying staking rules for trusts and funding automobiles. Additionally, allowing mark-to-market accounting for eligible digital property, simplifying charitable donations of usually traded cryptocurrencies. It additionally proposes recognizing blockchain growth as eligible analysis and growth exercise for tax credit.
The group additional advocates a statutory secure harbor for international traders buying and selling digital property on U.S. exchanges. Here, they argue that clearer tax rules may appeal to liquidity, encourage companies to stay within the U.S, and stop innovation from shifting offshore.
The unsaid caveat
However, it is crucial to notice that these proposals haven’t but been enacted into regulation.
Instead, they only symbolize the Blockchain Association’s suggestions to Congress, and any modifications would require legislative motion earlier than taking impact.
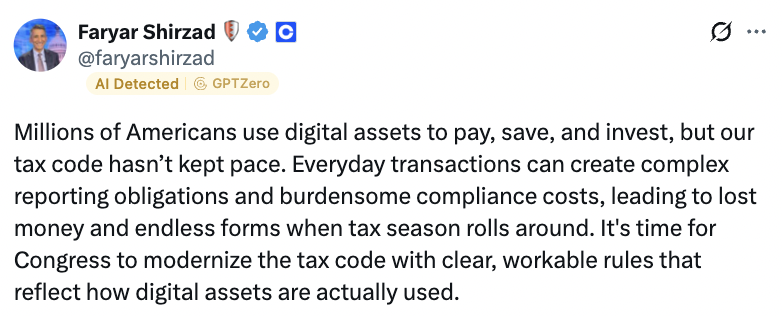
Still, Coinbase CPO applauded this transfer when he famous,
Notably, this coincided with the Blockchain Association (BA) submitting a comment letter to the U.S. Treasury on proposed GENIUS Act rules, whereas warning towards extreme compliance burdens on crypto companies, exchanges, and DeFi platforms.
Interestingly, all of this follows the U.S. CFTC, led by Chairman Michael Selig, plans to deliver extra of the crypto market under a unified federal framework after the CLARITY Act failed to advance in September.
Final Summary
- Blockchain Association outlined its Digital Asset Tax Principles and known as for bipartisan laws.
- All the solutions given by BA are simply suggestions to Congress and will not be but accounted for as regulation.