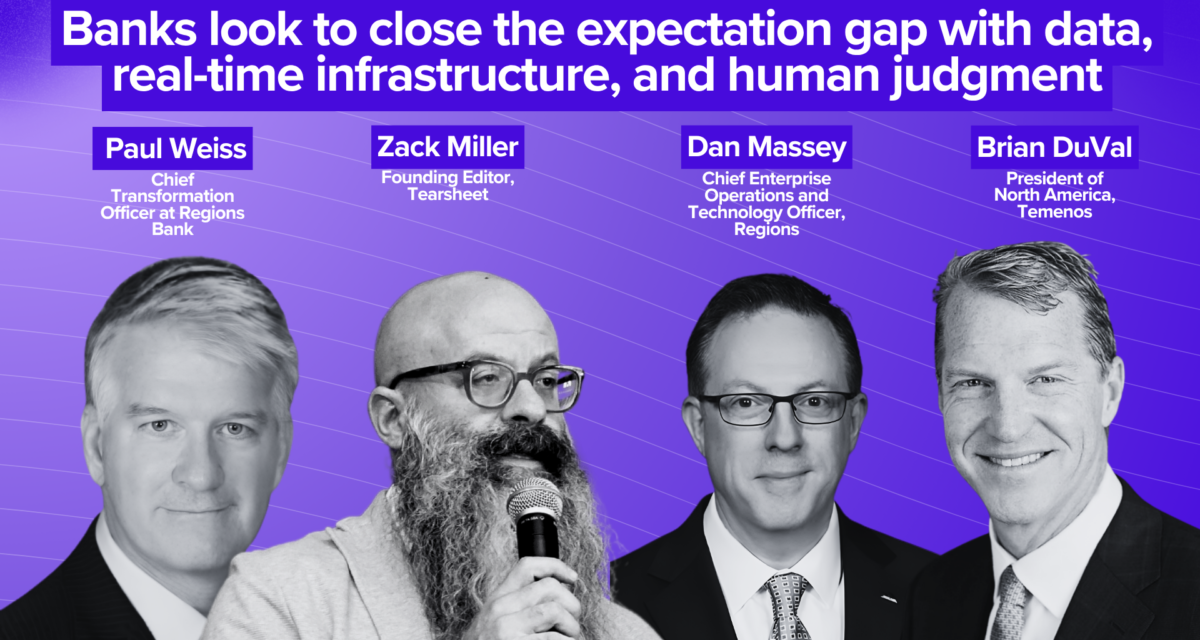

Customers maintain their banks to a regular they discovered elsewhere. Brian DuVal, President of North America at Temenos, factors to the velocity and ease of use they’ve grow to be accustomed to reserving a resort, renting a automotive or shopping for with one-click on Amazon. Yet their banking experiences don’t all the time measure up.
This distance is the topic of “The Banking Expectation Gap: U.S. Consumer Edition,” analysis commissioned by Temenos. It factors to a widening gap between what shoppers anticipate and what many establishments can ship, notably in personalization, belief, digital expertise, and well timed human assist. Paul Weiss, Chief Transformation Officer at Regions Bank, doesn’t anticipate the gap to cease widening by itself. “I don’t see the pace of change that has driven that gap slowing down,” he mentioned.
For Dan Massey, Chief Enterprise Operations and Technology Officer at Regions, the place to begin is the data banks already maintain. “Data is at the heart of that,” he mentioned, referring to serving to purchasers construct monetary confidence. Closing the gap will depend on whether or not a financial institution can put that information to work on a consumer’s behalf.
In a latest Tearsheet podcast, Massey, Weiss, and DuVal mentioned how this performs out in apply, from core platform funding and AI governance to personalization and funds.
Watch the full podcast
Listen to the full podcast
Subscribe: Apple Podcasts I SoundCloud I Spotify
Legacy information turns into helpful when the basis modifications
Banks maintain a belief benefit over newer fintechs, and that very same longevity creates a technical downside. “Sometimes that data can be locked in some legacy systems, some really old technology that’s tough to get it out,” mentioned Massey. Strategic capital allocation towards platforms that may flip information into one thing purchasers worth, whereas giving AI engines the inputs they want, may be the reply.
Weiss described the basis as a set of capabilities: clear information, real-time interactions delivered in a cloud-native and scalable method, and companies that may be composed into new consumer experiences. Building them is sluggish work. “Those aren’t easy to do as a series of incremental steps off of your business as usual platform,” he mentioned.
Regions’ work with Temenos on its core platforms is a part of that effort. A real-time, event-driven structure with a powerful API layer will allow a aggressive benefit, and it’s the base for the personalization the financial institution desires to supply.
AI begins in managed settings with individuals in the loop
Regions started making use of generative AI in the again workplace, the place builders have seen “probably about a 30% efficiency rate,” in accordance to Massey. The financial institution has additionally deployed clever doc processing and knowledge-base brokers. It has layered generative AI onto current analytics, together with a business instrument known as RClick that assesses the well being of business purchasers, so relationship managers can question it by way of a conversational interface. The financial institution has additionally deployed agentic instruments that scan the financial institution’s atmosphere for vulnerabilities and write code that builders can deploy shortly.
Each use case goes by way of danger and cybersecurity overview in parallel. “We’re very much a human-in-the-loop organization at this point,” Massey mentioned, including that the objective is to construct patterns that may be repeated and scaled.
Weiss laid out the sequence. “You have to start with your risk and your security partners with you out of the gate,” he mentioned, adopted by a governance framework, risk modeling of every use case, and an structure with safety and danger protocols inbuilt. He additionally suggested staying centered. “It’s easy to get distracted by shiny objects,” he mentioned, so enterprise-level priorities ought to decide which use circumstances get constructed.
DuVal mentioned clients have accepted the expertise however need to perceive the way it works. “Customers don’t mind if you’re using AI,” he mentioned, however they need transparency about the way it makes use of their information and handles their cash. As a response, Temenos has constructed copilots for financial institution customers and a monetary crime mitigation agent, reflecting rising issues about fraud and artificial content material.
Personalization extends throughout the entire relationship
Massey mentioned many banks supply a slim set of insights drawn from transaction exercise. Regions desires a wider view. “We want to help people with their larger financial relationship versus individual products,” he mentioned. The ensuing insights could be out there throughout digital channels and to contact middle brokers, frontline bankers, relationship managers, and wealth advisors.
According to Weiss, the trade has finished a great job bringing transactional capabilities into digital channels. The subsequent alternative is to add recommendation and perspective and transfer from static processes to clever workflows, which will depend on real-time capabilities and clear information.
Gen AI developments additionally make it attainable to serve clients as a section of 1, in accordance to DuVal. He recounted receiving weekly mailers from competing banks providing just a few hundred {dollars} to change accounts. The affords carry “no longer-term value that makes that sticky,” he mentioned. Banks already know loads about their clients, together with the place they reside, the ages of their kids, and once they is perhaps approaching faculty or retirement. They might use that data to ship extra related monetary planning steering.
DuVal additionally pointed to a gap in how banks deal with purchasers. Most have premium packages for his or her top-tier clients, however he requested about “all the ones in the middle that could be their next.” Those purchasers, he mentioned, are “one of one,” and AI makes it possible to serve them that method.
Payments mix safety and comfort
Moving cash in actual time additionally offers dangerous actors much less time to be stopped, so Regions has invested in id verification, third-party fraud controls, and conventional and generative AI instruments for fraud prevention. It can be rolling out passkeys for business, small enterprise, and client clients.
On the matter of comfort, Massey attracts an analogy from the transport trade. An in a single day provider doesn’t ask whether or not a package deal ought to journey by boat, aircraft, or truck. It asks, “Where do you want it to go? When do you need it to get there?” Banks, he mentioned, ought to do the similar and select amongst ACH, wire, and real-time fee rails on the buyer’s behalf.
For business purchasers, integration is a key precedence. Regions is working with fintech companions and leveraging its API layer to ship reporting and cash motion “directly into your ERP system,” so purchasers don’t want to go to a separate banking portal. The similar infrastructure additionally positions the financial institution to reply to rising demand for stablecoins and tokenized deposits.
Payments deliver many expectations collectively, and the tempo of change makes structure a long-term dedication. “You’re going to have to architect for flexible, rapid, ongoing change for forever,” Weiss mentioned.
Relevance and belief form the subsequent three years
Personalized relevance, safety, and belief are rising as the expectations more than likely to reshape regional banking over the subsequent three years. Fundamental banking merchandise “can be commoditized pretty easily,” in accordance to Massey. The differentiator, he sees, is the potential to transfer cash securely and conveniently in actual time whereas providing insights tailor-made to every consumer, whether or not it’s a client, wealth consumer, small enterprise, or company. Massey’s objective is to “help people live a happy life” and spare them fear about the cash facet.
DuVal framed the enterprise case by way of pockets share. Many banks, he mentioned, assume purchasers are staying as a result of they haven’t switched. In actuality, these clients might maintain a checking account at one establishment whereas holding retirement accounts, insurance coverage, and investments elsewhere. “They’re going to have assets everywhere,” he mentioned. “If they trust the institution, they would do it there if it was easy.” A financial institution that serves as a trusted advisor, with digital instruments that complement its individuals, has the likelihood to seize extra of that exercise.
“It’s easy to forget if you’re not careful that this is a human business,” mentioned Weiss. As the instruments grow to be extra succesful, the alternative is to assist clients succeed past facilitating a transaction on a telephone, and getting the basis and the fundamentals proper is the path to that. “Better and easier is a good combination,” he mentioned, “and I think we’re tracking well to that.”