
African policymakers and monetary specialists have known as for a fairer evaluation of the continent’s economies, stronger debt administration capability and higher transparency in credit standing methodologies, warning that persistent danger premiums proceed to lift borrowing prices and constrain growth financing.
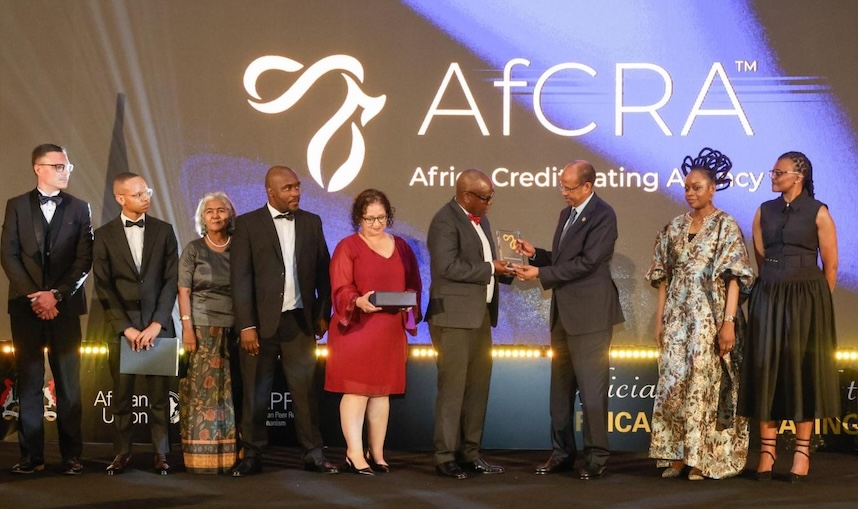
The name comes as Africa seeks to strengthen its voice in international credit score assessments following the launch of the Africa Credit Rating Agency (AfCRA) in Mauritius this month, towards the backdrop of mounting debt pressures, a projected international shortfall of 800 million jobs and rising calls for for infrastructure and social funding.
Also on Friday, the International Monetary Fund (IMF) warned that rising debt-service burdens have been squeezing growth spending, whereas the World Bank Group highlighted the problem of making jobs for a quickly rising international workforce, with a projected shortfall of 800 million jobs over the subsequent 10 to fifteen years.
Speaking on the 2026 IMF/World Bank Annual Meetings in Bangkok, IMF Managing Director Kristalina Georgieva warned that prime and rising curiosity burdens, notably in low-income nations, have been leaving governments with much less room to finance growth.
On his half, World Bank Group President Ajay Banga, burdened the necessity to mobilise non-public capital, broaden infrastructure and create jobs, disclosing that the establishment mobilised $112 billion in non-public capital final yr.
The new continental credit standing company is predicted to enrich current worldwide credit standing companies by incorporating extra African knowledge, experience and views into assessments of the continent’s economies. However, stakeholders say its success will rely upon its independence, credible methodologies, dependable financial knowledge and acceptance by traders.
Speaking at a panel dialogue on ‘The Debt Sustainability Framework, Credit Ratings and Africa’s Risk Premium,’ held on the sidelines of the IMF/World Bank Annual Meetings in Bangkok, Thailand, the Director-General of the West African Institute for Financial and Economic Management (WAIFEM), Dr. Baba Musa, mentioned African nations had spent many years calling for his or her financial realities to be assessed precisely and proportionately.
He mentioned African nations pay extra to borrow than comparable economies in different areas, arguing that prevailing perceptions and exterior interpretations of the continent’s financial realities usually positioned it at an obstacle.
“For a rating agency, the methodology should be comparable with international standards. However, what African countries have been asking for over the past 20 years is that they should be assessed accurately, their risks communicated proportionately, and their economies evaluated fairly,” Musa mentioned.
He burdened that the demand for fairer assessments was not a name for preferential therapy or decrease requirements, however for methodologies that adequately mirrored the variety, sources and financial circumstances of African nations.
“Africa’s voice should be heard and the continent should be assessed fairly, just like any other region,” he mentioned, including that AfCRA’s success would rely upon transparency, credible methodologies and its skill to seize the precise realities of African economies.
The price of Africa’s danger premium stays substantial. The Deputy Executive Secretary and Chief Economist of the United Nations Economic Commission for Africa (ECA), Dr. Hanan Morsy, estimated that persistent danger premiums price the continent roughly $75 billion yearly in extra curiosity funds.
The further borrowing prices come at a time when governments face mounting strain to finance growth, enhance dwelling requirements and create jobs for quickly rising populations.
Morsy mentioned African nations should additionally take higher duty for presenting evidence-based accounts of their economies somewhat than counting on others to make their case.
“If you do not advocate for yourself, no one will. This applies to individuals as well as countries. You must make your case and ensure that it is not based on words alone but backed by evidence,” she mentioned.
She emphasised the necessity for dependable knowledge to restrict the room for discretion in credit score assessments, warning that nations should be ready to supply the proof wanted to assist their financial outlooks.
Morsy added that worldwide establishments had helped nations with out earlier credit score rankings acquire them and subsequently enhance their rankings, whereas additionally supporting nations looking for investment-grade standing.
The launch of AfCRA is predicted to broaden the data obtainable to traders and supply further views on African economies, reform programmes and progress prospects. However, stakeholders have cautioned that the company’s institution alone won’t mechanically cut back borrowing prices with out stronger financial fundamentals and institutional credibility.
Beyond credit score rankings, African policymakers known as for reforms to debt sustainability assessments to make sure that the fashions and assumptions utilized by worldwide monetary establishments adequately replicate nationwide financial circumstances.
Musa welcomed facets of the revised Debt Sustainability Framework (DSF), noting that distinguishing between exterior debt misery, total public debt misery and precise debt unsustainability represented progress in assessing African nations’ debt positions.
He defined that nations experiencing liquidity pressures shouldn’t essentially be assessed in the identical approach as these dealing with solvency issues. Indicators resembling gross financing wants relative to gross home product and authorities income, he mentioned, might present a extra nuanced image of nations’ debt positions.
However, he known as for African governments to have a higher function in debt sustainability assessments, arguing that nations ought to collectively decide the assumptions and projections used to judge their debt positions.
Musa warned towards conditions by which the IMF and World Bank relied on their very own projections whereas African governments maintained totally different estimates of their financial outlooks.
Former Finance Minister of Niger Republic, Hon. Ahmat Jidoud, mentioned the revision of the DSF shouldn’t mark the top of efforts to enhance debt evaluation throughout the continent.
He known as on the IMF and World Bank to interact extra carefully with African nations, clarify the fashions and assumptions underpinning the framework, and supply coaching to officers in finance ministries and different related establishments.
Jidoud additionally raised considerations in regards to the therapy of home debt below the revised framework, notably its implications for regional financial communities such because the West African Economic and Monetary Union and the Central African Economic and Monetary Community.
For the Chief Executive Officer of the African Legal Support Facility (ALSF), Dr. Olivier Pognon, stronger coordination and knowledge-sharing amongst African establishments are important to enhancing the continent’s engagement with credit standing companies and strengthening debt administration.
Pognon mentioned the ALSF was creating a capacity-building platform anticipated to be launched in Abidjan, Côte d’Ivoire, on the finish of November. The initiative would assist debt administration places of work and officers concerned in public borrowing and main undertaking negotiations.
IMF Warns Debt Burdens Squeezing Development
The debate over Africa’s borrowing prices comes because the IMF warns that rising public debt and curiosity funds are limiting governments’ skill to finance growth and reply to financial shocks.
Speaking on the Annual Meetings Plenary, Georgieva, mentioned low-income nations confronted notably tough circumstances, with excessive and rising curiosity burdens compounded by declining official assist.
“Too many countries carry too much debt,” she mentioned, warning that debt-service obligations have been crowding out growth spending.
Georgieva mentioned governments couldn’t depend on financial progress alone to reverse rising debt trajectories rapidly sufficient and known as for credible medium-term fiscal plans to revive stability.
“The inescapable bottom line is that preserving stability requires fiscal consolidation in most high-debt countries,” she mentioned.
However, she cautioned that fiscal changes should defend weak households, restrict the fee to future progress and be complemented by structural reforms that enhance productiveness.
World Bank mobilises $112bn in non-public capital
Banga, in the meantime, highlighted the necessity to mobilise non-public capital, broaden infrastructure and create jobs for a quickly rising younger inhabitants.
He mentioned 1.2 billion younger individuals have been anticipated to enter the labour market over the subsequent 10 to fifteen years, whereas the worldwide financial system was projected to generate solely about 400 million jobs, leaving a possible shortfall of 800 million.
“The jobs gap is a projection. It does not have to be our future,” Banga mentioned.
He argued that closing the hole would require nations to make higher use of scarce sources by combining public finance, non-public funding, philanthropy and know-how to assist growth.
Banga disclosed that the World Bank Group mobilised $112 billion in non-public capital final yr, in contrast with roughly $35 billion in monetary yr 2022. Total financing, together with the establishment’s personal sources, exceeded $230 billion.
However, he acknowledged that attracting industrial funding remained tough in low-income nations, the place non-public capital mobilisation stood at roughly $3 billion.
He mentioned the World Bank was looking for to broaden financing for micro, small and medium-sized enterprises by enhancing entry to finance, connecting smaller companies to bigger markets and simplifying rules that constrain progress.
Banga additionally recognized infrastructure, human capital and regulatory certainty as important foundations for job creation, noting that companies wanted dependable electrical energy, water, transport and digital connections, whereas employees required schooling, healthcare and related expertise.
On electrical energy entry, he mentioned the World Bank Group and the African Development Bank have been working to supply electrical energy to 300 million individuals throughout Africa by 2030 below Mission 300.
So far, 59 million individuals have gained entry, with the tempo accelerating from 12 million in monetary yr 2024 to 18 million in monetary yr 2025 and 28 million within the newest monetary yr.
“But access is only part of the challenge. Homes, mines, factories, farms, and growing cities need reliable, affordable baseload power,” he mentioned.
Stakeholders additionally burdened the necessity for accountable fiscal insurance policies, stronger home useful resource mobilisation, improved debt administration and higher coordination between African governments and worldwide monetary establishments.
Nume Ekeghe in Bangkok, Thailand
Follow us on: